Okay besties, Cisco just posted a killer quarter and still got punished by the market — let’s unpack why, because this is actually a great money lesson.
The quarter was, objectively, a win
After market close Thursday, Cisco Systems (CSCO) reported its first quarter of fiscal 2027 with $18.5 billion in revenue — an all-time high, and up 24% year over year. Adjusted (non-GAAP) net income jumped even harder: 39% growth, landing at $5.6 billion, or $1.40 per share.
Both numbers beat analyst estimates, though not by a landslide. Wall Street was modeling roughly $18.1 billion in revenue and $1.32 in adjusted EPS. Cisco cleared both bars.
Here’s what I’d point out to my coaching clients: the growth engine here is one you already know and love from every headline — AI. Companies building out AI compute capacity are buying Cisco’s networking gear, and that’s driving the top line. On the bottom line, profitability got a boost from a leaner workforce (yes, layoffs helped margins — not exactly feel-good, but it’s how the math worked).
CEO Chuck Robbins put it plainly in the earnings release, saying organizations are turning to Cisco to scale, secure, and optimize for what he calls the agentic AI era. His bigger claim? We’re in the very early stages of a multi-year networking supercycle, one representing a multi-billion-dollar opportunity for Cisco.
And management didn’t just talk the talk — they raised guidance. Full-year fiscal 2027 revenue is now expected at $74.8 billion to $75.8 billion, up from the prior forecast of $72.2 billion to $73.4 billion. Adjusted EPS guidance moved up to $5.47–$5.53 from $5.05–$5.11.
A beat AND a raise. On paper, that’s a stock that should’ve popped the next morning.
So why did the stock drop more than 6%?
This is the part that makes investing feel confusing — and where I want you to pay attention, because understanding this dynamic will make you a better investor forever.
The market isn’t grading your report card against the past. It’s grading against expectations, and expectations for tech hardware companies right now are sky-high. Investors found a few things in the report that worried them.
First: product orders. For a hardware company, orders are like appointments on the books at a salon — they tell you what future revenue looks like. Total product orders grew 21% year over year. Solid! But the previous quarter (Q4 of fiscal 2026) saw 35% growth, inflated by hyperscaler clients who went on an ordering spree to the tune of $4 billion. Still, a sharply slowing growth rate is exactly the kind of thing hardware shareholders hate to see, even when there’s a reasonable explanation.
Second: margins got squeezed. Adjusted gross margin slipped to 65.6% from 68.1% a year ago, thanks to pricier memory components and a bigger mix of lower-margin AI networking products in the revenue pie. Think of it like your favorite boutique raising prices on materials — even if sales are booming, each sale is a little less profitable.
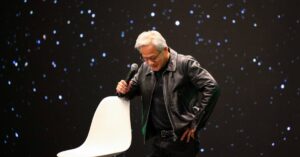
Third — and this one isn’t even Cisco’s fault — is the Jensen Huang situation. Nvidia’s longtime co-founder and CEO stepped down after becoming embroiled in a scandal involving an alleged spy from China, and the fallout is rattling AI-industry stocks broadly. Cisco and Nvidia compete in some segments but partner in several hardware segments too, so anytime a leader as central as Huang exits, questions about strategic continuity pop up. To be fair: there’s been no sign interim CEO Colette Kress plans to shake things up — but she also hasn’t publicly pledged loyalty to Huang’s vision either. Uncertainty is kryptonite for stock prices, even when it’s someone else’s drama.
Looking ahead, CFO Mark Patterson also flagged on the earnings call that the second half of the fiscal year will bring tougher compares and a little less visibility. Translation: the growth numbers might not look as jaw-dropping as we slide into next year.
Here’s my take, as your financially savvy bestie
I think the negatives overshadowed what was genuinely a strong report — double-digit revenue growth, big profitability, a meaningful guidance raise, and management conviction that the growth continues. That’s not a broken company. That’s a good quarter that didn’t clear an impossibly high bar.
And here’s the nuance I want you to internalize: AI infrastructure spending is lumpy. When there’s a frenzy — an arms race, essentially — orders don’t arrive in a smooth, tidy line. Some quarters the hyperscalers front-load their buying, and the next quarter looks slower by comparison. A 21% order growth rate being treated as a red flag tells you more about inflated expectations than about Cisco’s actual business.
That’s why I tell my coaching clients: don’t let one day’s stock reaction dictate your read on a company. The market’s mood swings are not the same thing as fundamentals. Cisco has been a trusted hardware supplier for decades, and right now you’re looking at a beat-and-raise quarter paired with a 6%+ discount.
If I were building a position, this is the kind of moment I’d actually get interested — a quality, established name temporarily marked down because of optics, margin math, and someone else’s CEO scandal. Not financial advice, not a shopping list — just the framework: buy businesses, not stock charts, and let the market’s overreactions work in your favor over the long run.
One earnings report, one red candle, zero change to the long-term story. That gap? That’s where opportunity lives. 💛
If you want more of these no-fluff breakdowns — and help building a portfolio that matches your actual goals — come hang out with me! DM me your biggest money question or join my mailing list so you never miss a stock story worth knowing about. Your future rich-girl self will thank you. ✨